In plain words
Think of a shop. The till, the website and the staff are what customers see. Behind them is the stock system, which knows exactly what is on every shelf and what came in and went out today. If the stock system is wrong, nothing in front of it can be right.
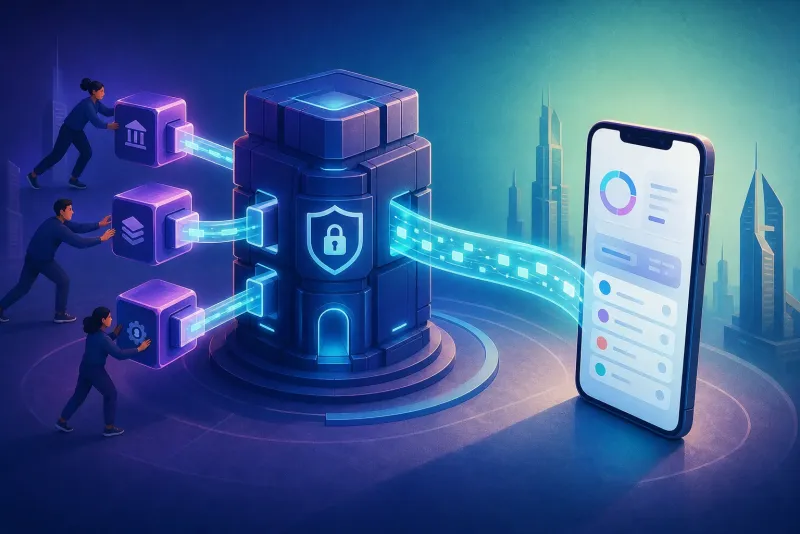
Core banking is that stock system for money. It keeps every customer account, every balance and every transaction. It applies the rules of each product: how much a transfer costs, how much a customer can spend in a day, when interest is added, what happens when an account is frozen. The mobile app, the cards, the payment connections and the back office all ask it questions and send it instructions.
At its heart is the ledger, the record of every movement of money. Everything else in the core is built to keep that record complete, consistent and explainable.
How it works
How core banking handles one payment
A customer sends £50 from the app. This is what the core does with it.
-
1
The app sends an instruction
Through an API, the app asks the core to pay £50 from the customer’s account to a named recipient.
-
2
The core checks the rules
Is the account active, is there enough money, is the payment within the daily limit, what fee applies? If any check fails, it stops here.
-
3
The ledger records it
The £50 and the fee are posted as debits and credits. The balance updates at once, and the record can never be quietly changed, only corrected by a new entry.
-
4
The payment goes out and is reconciled
The payment is sent through a payment rail. Later the core matches it against the bank or partner’s records in daily reconciliation.
What a core banking system covers
Vendors draw the line in different places, but most cores cover the same set of jobs.
Customers and accounts
Who owns which account, in which currency, with which status and permissions.
Ledger and balances
Every posting, every balance, in real time, with a full history.
Products and pricing
Fees, limits, interest where allowed, and the rules that differ by customer tier.
Transaction lifecycle
Pending, completed, reversed, refunded: each payment’s state from start to finish.
Reporting and audit
Statements, regulatory reports and an audit trail of who changed what, and when.
Integrations
Connections to payment rails, card processors, KYC and FX providers, and to the app.
Four ways to get a core
There is no single right answer. The choice depends on your licence route, your product and how much of the logic you want to own.
| Option | What it means | Good for | Watch out for |
|---|---|---|---|
| Traditional core | Established software designed for banks, often installed and heavily customised | Licensed banks with large IT teams | Long projects, batch processing, high cost to change |
| Cloud-native core | A modern core licensed as a service, configured through APIs | Licensed firms that want speed and scale | Fees that grow with accounts, vendor lock-in |
| Partner’s core | Your BaaS partner’s system holds the regulated accounts | Launching without a licence | Your product is limited to what the partner supports |
| Your own core | Built for you, or from a codebase you own and extend | Products with unusual logic or plans to change partners | Needs strong engineering and testing discipline |
Even on a partner’s core, most teams still run their own ledger and product layer on top. It is what lets them reconcile independently and move partners later. Read banking system code for a neobank for the ownership questions to ask.
What regulators expect, in the UK, EU and Gulf
No regulator tells you which core to use. They care that it keeps working and that you stay in control of it, even when a supplier runs it.
- United Kingdom. The FCA and PRA operational resilience rules ask firms to identify their important business services, set tolerances for disruption and test that they can stay within them. A core banking outage hits almost every important service. 1
- European Union. DORA, applying since January 2025, sets rules for IT risk, incident reporting, testing and oversight of technology suppliers, including the contracts you sign with a core vendor. 2
- Gulf. Central banks in the UAE and Saudi Arabia set their own outsourcing, cyber security and data rules, and some data may need to stay in the country. Check where your core and its data will be hosted before you choose it.
Example: adding a second currency
Nadia runs a UK wallet for small importers. Customers now want to hold euros as well as pounds.
- Accounts. Her core opens a euro account next to each customer’s pound account, linked to the same customer record.
- Pricing. She adds an FX fee and a daily conversion limit as product rules, without changing app code.
- First conversion. A customer converts £1,000. The ledger posts the pound debit, the euro credit and the fee in one balanced entry.
- Reconciliation. Each morning the core matches both currency balances against her partner’s accounts and flags any difference for her finance team.
Common misconceptions
“If I use BaaS, I do not need a core.”
The partner’s core holds the regulated accounts, but you still need your own record to apply your fees and limits, show balances and reconcile.
“A core is just a database of balances.”
Balances are the output. The hard part is the rules, the transaction states, the corrections and the audit trail that explain every number.
“We can change the core later.”
You can, but migrating live accounts and years of history is one of the most expensive projects a financial firm undertakes. Choose with growth in mind.
FAQ
What is a core banking system?
It is the central software that holds customer accounts, balances and transactions, and applies the product rules for fees, limits and interest. Apps, cards, payments and the back office all connect to it.
What is the difference between core banking and a ledger?
The ledger is the record of every money movement, from which balances are calculated. Core banking includes the ledger and adds the accounts, products, rules and processes built around it.
Does a neobank need its own core banking system?
Not always. A neobank on a BaaS partner can rely on the partner's core for the regulated accounts, but it still needs its own ledger and product logic to show balances, apply its own fees and limits, and reconcile with the partner.
Should we build or buy core banking?
Most early-stage teams buy or license a core, or start from a ready codebase they can extend, because building one from scratch takes a long time and is hard to get right. Building your own makes sense when your product logic is unusual and core to your advantage.
How long does a core banking migration take?
It depends on the size and age of the data, but it is usually measured in months or years, not weeks. Choosing a core you can keep as you grow is cheaper than migrating later.
What should I ask a core banking vendor?
Ask whether it supports your currencies and products, how it handles real-time balances and reconciliation, who owns the data and code, how you can exit, and how it meets the operational resilience and outsourcing rules your regulator applies.
Related terms
Sources
-
1
FC
Financial Conduct Authority Operational resilience
https://www.fca.org.uk/firms/operational-resilience -
2
EL
EUR-Lex Regulation (EU) 2022/2554 on digital operational resilience (DORA)
https://eur-lex.europa.eu/eli/reg/2022/2554/oj